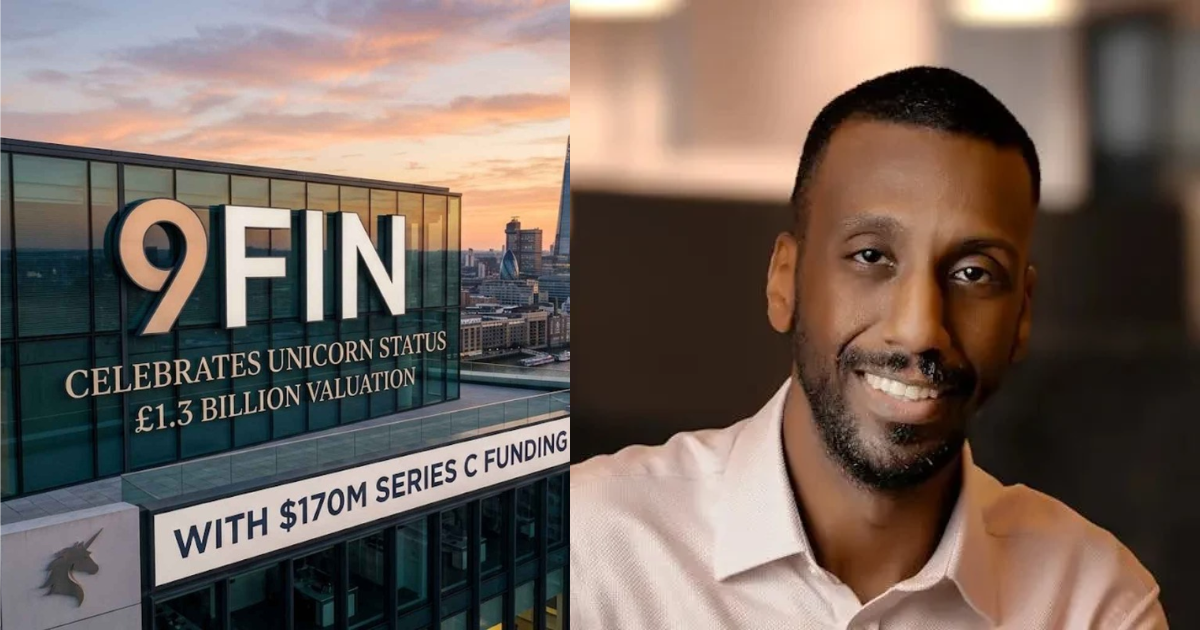
On March 31, 2026, 9fin announced a $170 million Series C and a $1.3 billion valuation. The London company sells information and software to people who analyze corporate debt: bankers, credit investors, lawyers and advisers. The round put 9fin in the unicorn club. Its business rests on a practical test: whether professionals keep paying for the service.
HarbourVest led the raise. Canada Pension Plan Investment Board (CPP Investments), Highland Europe, Spark Capital, Redalpine and Seedcamp also participated. The British Business Bank said it would invest $20 million as part of the round, in partnership with Redalpine. It reported that more than 300 banks, asset managers, law firms and advisory firms use 9fin’s platform.
A Company Built Around Debt-Market Information
9fin was founded in London in 2016 by Steven Hunter and Hussam El-Sheikh. Hunter had worked at J.P. Morgan and Babson Capital Management; El-Sheikh had worked as an engineer at Deutsche Bank. Hunter’s company profile describes his work covering European high-yield bonds and leveraged loans before 9fin.
The founders knew a market where analysts and investors move between filings, emails, news reports, loan documents and private data rooms. Researching a borrower can mean piecing together material from several places. 9fin aims to bring much of that work into one platform.
It covers leveraged loans, high-yield bonds, distressed debt, collateralized loan obligations and private credit. The company says AI helps search and organize information, extract details from documents and support research. The software still depends on specialized information collected, checked and presented for credit professionals.
Hunter described the original problem in the company’s 2024 Series B announcement:
We started 9fin to give professionals in the market a data edge, with smarter, faster intelligence.
— Steven Hunter
The platform may save time by reducing searches across systems for a covenant, filing or restructuring update. Public sources do not show whether subscribers consequently make better investment decisions.
The Customer Base Behind the Funding
In December 2024, 9fin said it served nearly 200 large firms. By March 2026, the British Business Bank reported more than 300 client institutions. The company also said CPP Investments had been a client before joining the Series C as an investor. That is a notable link between product and financing: an institutional customer later took part in backing the company.
Highland Europe led 9fin’s $50 million Series B in 2024, joined by existing investors including Spark Capital, Redalpine and Seedcamp. At the time, 9fin reported nearly 200 customers and more than $17 trillion in combined assets under management among asset managers using its platform. The company said it would use the funding for technology, analytics hires and US expansion.
For a subscription software company, repeat use matters. A service that becomes part of analysts’ research and monitoring may be harder to replace than a tool used occasionally. Teams could face retraining and workflow changes if they switch systems.
9fin reports several consecutive years of 100% annual recurring revenue growth and calls its retention industry-leading. It has not published the churn figures, subscription prices or calculation details needed to assess those claims independently.
The model has an appealing shape: recurring contracts can make income more predictable, while a shared data product can serve many users inside one institution. But the costs are recurring too. The company must maintain the data, software and specialist coverage that keep the service useful.
Revenue Is Growing; So Are the Costs
The $1.3 billion valuation came from a private funding round. It is not the company’s revenue, cash balance or profit, and it does not show how much of 9fin its founders still own. The distinction matters when a large valuation is treated as a measure of how much money a business has made.
9fin’s filed group accounts offer a more direct view of its operating scale. For the year ended December 31, 2025, the company reported turnover of about £31.4 million, up from about £14.7 million in 2024. It also reported an operating loss of roughly £22.3 million in 2025.
Revenue more than doubled while costs remained high. The group averaged 345 employees in 2025, supporting research, engineering, sales and service across markets.
9fin expanded through acquisition as well. In 2025 it bought Bond Radar, a provider of international bond and loan-market intelligence. The deal brought another data business into the group, potentially extending its coverage while adding integration work and cost.
What Founders Can Take From the Case
For Black American founders, 9fin is a business case about a specialized market, not a story about a Black-led company. Its path raises practical questions that apply across sectors: Who experiences the problem? Who controls the budget? How often does the need recur? What does the customer already spend to address it?
The founders had direct experience in credit markets and built for professionals whose work depends on financial information. That knowledge gave them a starting point for defining the product and finding potential buyers. Founders entering unfamiliar industries may need customer interviews, pilot projects or advisers with real operating experience to develop the same understanding.
A niche can support a company when customers face a repeated problem and will pay for a reliable solution. 9fin’s public figures show rising turnover and a larger client base, but not customer-level profitability or whether the model would work in another sector.
For 9fin, the raise gives the company money to hire, develop its product and expand its data coverage. Investors gain a stake and may have governance rights, while founders and employees may see their ownership diluted. The round’s public announcement does not disclose the full terms or the founders’ remaining shares. A founder assessing an offer needs to weigh the cash available for growth against the control and ownership given up to obtain it.
The Work After the Unicorn Announcement
The funding round is complete. The company has also acquired Bond Radar, reported more than 300 institutional clients and published accounts showing higher turnover alongside an operating loss. Its plans to expand AI capabilities, proprietary data and US operations are forward-looking commitments, not completed outcomes.
The next stretch depends on execution. New data and AI tools will matter if customers find them accurate and useful in their actual research. Expansion into more markets will add opportunities as well as operating demands. The available figures do not yet show whether this investment will produce sustainable profits.
Hundreds of financial firms use 9fin, and investors have funded its next stage. The raise signals confidence in the company’s prospects. Whether the business becomes durable depends on customers renewing and revenue eventually covering the cost of serving them.
FAQs
What does 9fin do?
9fin provides debt-market data, news, analysis and document tools. Its platform serves banks, asset managers, law firms and advisers working in leveraged finance, distressed debt, private credit and other credit markets.
How much did 9fin raise?
9fin announced a $170 million Series C on March 31, 2026. HarbourVest led the round, which valued the company at $1.3 billion. The British Business Bank said it would invest $20 million as part of the financing.
Is 9fin profitable?
Its filed group accounts show turnover of about £31.4 million and an operating loss of roughly £22.3 million for 2025. The accounts show revenue growth, but they do not show a profitable business.
Who founded 9fin?
Steven Hunter and Hussam El-Sheikh founded 9fin in London in 2016. Hunter had worked in leveraged finance and credit investing. El-Sheikh had an engineering role at Deutsche Bank.
Why might financial firms keep using 9fin?
The platform brings together information credit professionals use in recurring research and monitoring. If it reliably fits those workflows, it can be valuable to customers. Public sources reviewed do not provide detailed churn or subscription-price data.
What can founders learn from 9fin?
The company shows how founders with industry knowledge can build a product around a recurring customer problem. Its growth does not prove that institutional software always beats consumer technology or that venture capital suits every business.